Axis Bank Q2: Top Profit Surge Projected Despite 7-12 Bps Margin Dip
Axis Bank Q2 preview: Analysts expect a 37-43% PAT jump, though NIM may dip 7-12 bps due to FCNR(B) deposit costs. Get the full earnings outlook here.
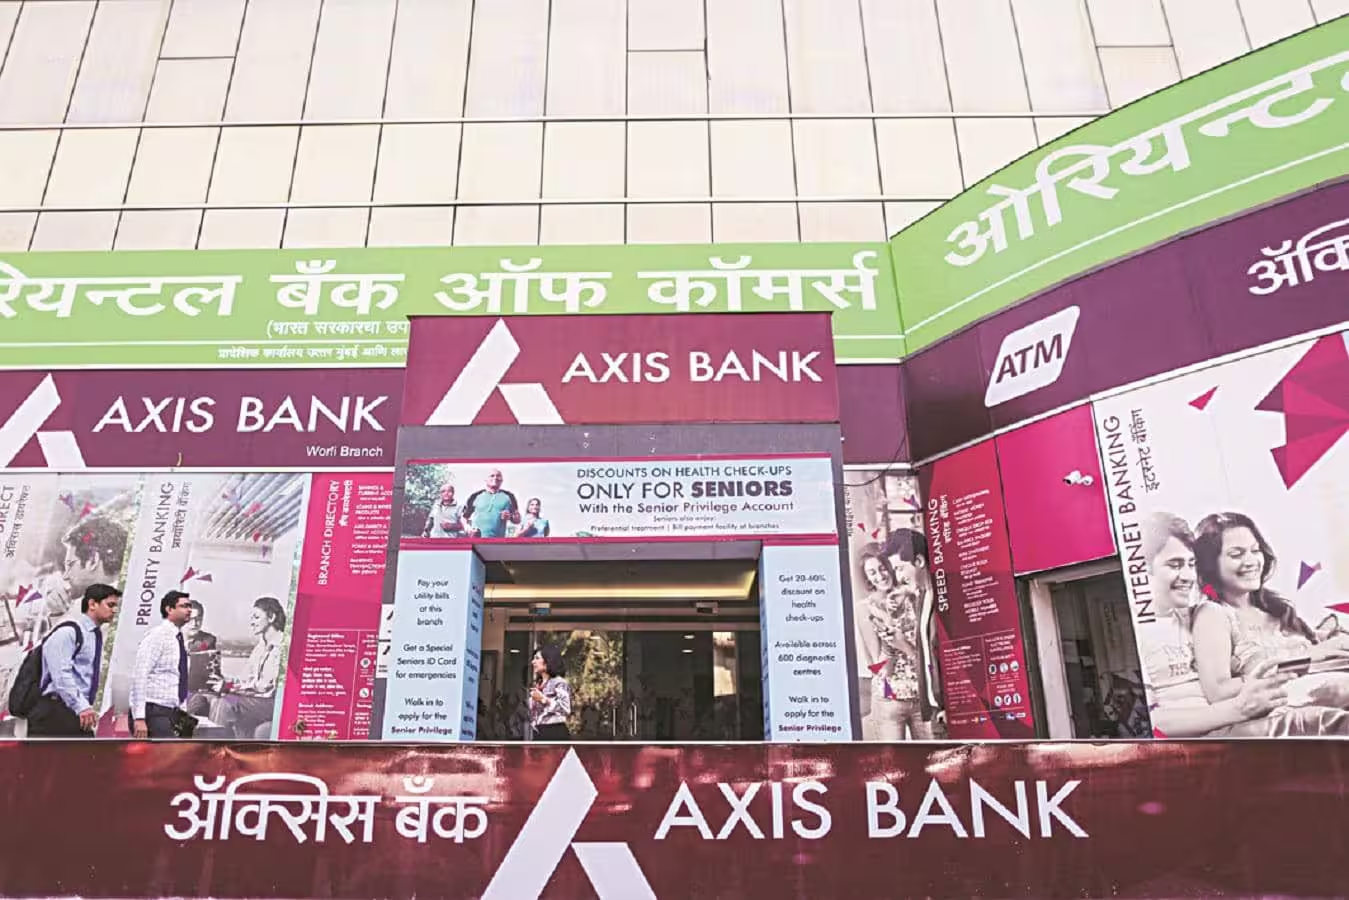
Financial analysts are currently finalizing their axis bank q2 projections as the lender prepares to report its quarterly performance. Market participants are closely monitoring the axis bank results preview to gauge how recent liquidity shifts impact core profitability. Despite some anticipated headwinds, the overall sentiment remains cautiously optimistic regarding the lender's growth trajectory.
Analyzing the Axis Bank Q2 Margin Outlook
The axis bank net interest margin is expected to face significant downward pressure during this reporting period. Experts suggest that a sequential decline of 7-12 basis points is likely for the bank. This compression is primarily linked to the increased mobilization of fcnr b deposits across the branch network.
High-cost liabilities often weigh on net interest margins during periods of aggressive liquidity gathering. Consequently, the axis bank q2 figures will reflect this tactical shift in the funding mix. Analysts will look for management commentary on how these flows might stabilize in the coming quarters.
Profitability Trends and Axis Bank Q2 Growth
Despite the margin compression, the bottom-line performance appears robust for the quarter. Projections indicate that the axis bank q2 profit could grow between 37% and 43% compared to the previous year. This expansion highlights the underlying resilience of the bank's core operational strategy.
Several factors are contributing to this strong earnings outlook
- Sustained growth in fee-based income streams.
- Improved cost-to-income ratios across major business units.
- Healthy credit demand supporting the top line.
The axis bank q2 performance will likely validate the bank's ability to navigate volatile interest rate environments effectively. Investors are keeping a close watch on these figures as they represent a key indicator for broader banking sector earnings.
Strategic Implications for Investors
The upcoming axis bank q2 release will provide deeper clarity on asset quality and loan growth. While the margin squeeze is a technical reality, the projected rise in net profit suggests strong volume growth. Market observers are eager to see if the axis bank q2 results align with these high expectations.
Successful execution of the bank's current strategy remains a focal point for institutional shareholders. Any deviation from these projections could influence short-term volatility in the stock price. Ultimately, the axis bank q2 report serves as a critical benchmark for the private banking landscape.
In conclusion, the bank faces a complex balance between deposit mobilization and margin protection. While the axis bank q2 results may show pressure on margins, the double-digit growth in profit underscores a resilient business model. Stakeholders should focus on the management's outlook regarding future deposit costs and balance sheet expansion.
More updates
Follow the latest Market news and related coverage.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Karan Bhatia is a business reporter who focuses on banking, real estate and the stock market. He explains how policy changes and market movements affect investors and families. His reports are well researched and easy to follow.

Comments (0)